BYD company and founder owner
Quick Answer: Wang Chuanfu is a materials engineer who turned BYD from a Shenzhen rechargeable-battery producer into a vertically integrated electric-vehicle and energy group. The decisive pattern was not one invention. It was a sequence: redesign battery manufacturing for constrained capital, list before entering cars, acquire a licensed automaker, endure years of weak automotive returns, and then combine LFP batteries, plug-in hybrids, vehicle electronics and manufacturing scale. BYD’s history is therefore both a founder story and a case study in how China’s industrial policy, engineering talent, supply chains and consumer market created a new kind of global automaker.
Last verified: October 11, 2026. Financial figures combine BYD’s audited 2025 annual report, the 2026 interim report (August 2026) and the September 2026 production and sales filing; launch performance figures are explicitly identified as company claims.
Page role: This is BYDToday’s single company-and-founder Owner for BYD and Wang Chuanfu. It preserves the existing canonical and combines the founder biography, corporate history and strategy in one durable page. Detailed battery, charging and assisted-driving claims route to specialist BYDToday Owners rather than being duplicated here.
| Date | Verified milestone | Strategic meaning | Evidence boundary |
|---|---|---|---|
| 1987–1995 | Wang completed materials-related study, worked in the Beijing nonferrous-metals research system, managed Shenzhen Beagle Battery and then started BYD. | The company began with electrochemistry and manufacturing, not automotive styling or retail distribution. | Official biography; founding date is explained below. |
| 2002 | BYD completed its Hong Kong H-share listing. | Public capital and disclosure discipline arrived before passenger-car entry. | BYD investor information. |
| 2003 | BYD acquired 77% of Xi’an Qinchuan Automobile for RMB269.5 million. | A battery maker obtained an automotive manufacturing platform and licensing base. | HKEX 2003 interim filing. |
| 2005 | The F3 passenger sedan launched. | Volume vehicle production became a commercial capability rather than a strategic idea. | BYD corporate timeline. |
| 2008–2009 | The F3DM plug-in hybrid debuted; MidAmerican agreed to subscribe for 225 million BYD H shares and completed the subscription in 2009. | Electrification and outside capital converged before plug-in vehicles were mainstream. | Product history and HKEX transaction records. |
| 2007–2011 | A second wave of reverse-engineered models (F0, F6, S6, M6) expanded the line-up; an over-extended four-network dealer system then produced the 2010–2011 channel crisis. | Copying built scale; distribution overreach became the first major governance test. | Model history and industry archives; dealer-exit counts vary by source. |
| 2010–2012 | e6 electric taxis entered service in Shenzhen and K9 electric buses began trials; a high-speed 2012 crash put the young technology under public scrutiny. | The fleet-first deployment generated the battery and durability data later product decisions drew on. | Official launch records; joint expert investigation conclusions (August 2012). |
| 2011–2019 | Revenue grew unevenly while profit repeatedly compressed; 2012 and 2019 were especially weak. | BYD’s later rise was built through a long, expensive transition rather than uninterrupted success. | Audited annual-report series. |
| 2020–2021 | Blade Battery and the DM-i hybrid platform launched. | Long investment in LFP chemistry and system efficiency became customer-facing product narratives. | Launch claims are not independent test results. |
| 2022 | BYD stopped producing gasoline-only vehicles and focused on battery EVs and plug-in hybrids. | The group concentrated the passenger-car portfolio on electrified drivetrains. | PHEVs still contain combustion engines. |
| 2023–2025 | BYD expanded a four-brand portfolio and sold 4.60 million NEVs in 2025, including 1.05 million overseas. | The operating problem shifted from proving electrification to coordinating brands, factories, logistics and software at global scale. | 2025 annual report. |
Wang Chuanfu before BYD: the engineer behind the founder story
BYD’s official biography dates Wang Chuanfu’s birth to February 1966 in Wuwei, Anhui. It says he completed a bachelor’s degree in metallurgical physical chemistry at the Central South University of Technology in 1987 and a master’s degree in engineering at the Beijing Nonferrous Metals Research Institute in 1990. He then worked as an engineer and deputy director in the research system before becoming general manager of Shenzhen Beagle Battery.
Those details matter because they locate Wang in China’s technical-institute system rather than in the usual consumer-technology founder template. His early expertise was in materials, electrochemistry and production. In practical terms, the central question was how to turn laboratory knowledge into stable, repeatable manufacturing with limited capital. That question later became BYD’s corporate method: understand a system deeply, redesign expensive steps, bring critical feedback loops inside the group and use manufacturing scale to make the technology economically useful.
The official record also requires one historical qualification. BYD’s current corporate timeline says the company was founded and registered on November 18, 1994, while Wang’s official biography and many company narratives describe February 1995 as the founding or operating start of Shenzhen BYD Industrial. This page preserves both dates instead of forcing one source to erase the other: 1994 is the corporate-origin date used in BYD’s current anniversary framework; February 1995 is the start date used in the founder biography and much of the historical literature.
1995–2001: the first advantage was battery manufacturing, not branding
BYD entered rechargeable batteries when established Japanese manufacturers possessed better-known brands, more automated equipment and deeper capital resources. Chinese company histories often compress this period into dramatic factory-floor anecdotes. The defensible core is simpler and more important: BYD treated the production process itself as an engineering problem. It decomposed expensive automated lines into controllable stages, designed or adapted equipment internally, and tried to preserve yield and consistency while using less capital.
This was not merely a low-wage strategy. Labour cost helped, but the reusable capability was process ownership. Engineers had to understand why each production step existed, how material quality changed downstream yield and where manual work could be standardized without losing control. BYD’s older official history says its lithium-ion battery sales exceeded RMB100 million by 1997, it became a Motorola supplier in 2000 and then supplied Nokia in 2002. Those customer milestones show that cost reduction alone was insufficient: international electronics customers also required quality systems and reliable delivery.
The battery years created three forms of institutional memory. First, BYD learned to industrialize chemistry rather than only license it. Second, it learned that internal equipment and process design could offset capital constraints. Third, it learned to connect materials, components and final-product requirements through one organization. The later automobile strategy reused all three. A car was far more complex than a battery pack, but Wang’s assumption remained consistent: if the group controlled enough of the technical stack, it could reduce coordination costs and move faster than a company assembling mostly external subsystems.
Historical boundary: Exact claims about the first factory’s headcount, loan size, machinery cost or line-by-line savings vary across retellings. They are useful leads for further archival work but are not treated here as audited facts.
2002: BYD listed before it became an automaker
BYD’s Hong Kong listing is sometimes presented as a footnote between batteries and cars. Strategically, the order matters. BYD completed its H-share listing on July 31, 2002, issuing 149.5 million shares including the over-allotment option at HKD10.95 per share. The company therefore entered public markets while investors could still understand it primarily as a fast-growing battery manufacturer.
The listing did more than raise money. It created a recurring disclosure record that makes BYD’s transformation unusually traceable. Subsequent filings show acquisitions, research expense, cash flow, debt, margins, ownership and geographic revenue. This evidence also corrects the heroic version of the story: capital-market access did not make the automotive transition easy, and later returns were volatile. But without the battery business and the credibility built before the vehicle acquisition, BYD would have faced a much narrower path into a capital-intensive industry.
2003: buying Xi’an Qinchuan changed the company’s risk profile
In March 2003, BYD acquired a 77% interest in Xi’an Qinchuan Automobile from Norinco for RMB269.5 million. BYD’s 2003 interim filing recorded fair value of net identifiable assets at RMB288.184 million. The acquired company had sold roughly 17,000 Flyer cars in 2002 and was renamed BYD Auto in May 2003. These numbers are more informative than the simplified statement that BYD “started making cars”: the group bought a small but functioning automaker with manufacturing experience and a marketable vehicle.
The acquisition was controversial because it changed BYD from a component specialist into a company responsible for complete vehicles, dealer relationships, safety, warranties and consumer brand perception. The risk was not only financial. Vehicle engineering required coordination across thousands of parts and much longer development cycles. BYD had to learn areas that battery expertise could not automatically solve.
Wang’s strategic logic can be inferred from what BYD built next, but it should still be labeled as interpretation. Electrified transport would require batteries, motors, power electronics and controls to work as one system; ownership of a vehicle platform gave BYD a place to integrate them. The acquisition therefore converted battery knowledge into an option on the future of mobility. It did not guarantee that BYD could make a competitive car.
2005–2008: the F3 proved volume manufacturing; the F3DM revealed the destination
The F3 sedan launched in September 2005. It was not the final expression of BYD’s technology strategy, but it established a more basic capability: developing, manufacturing, distributing and servicing a mass-market passenger car. That commercial platform mattered because a breakthrough drivetrain has limited value if the company cannot build and sell the rest of the vehicle.
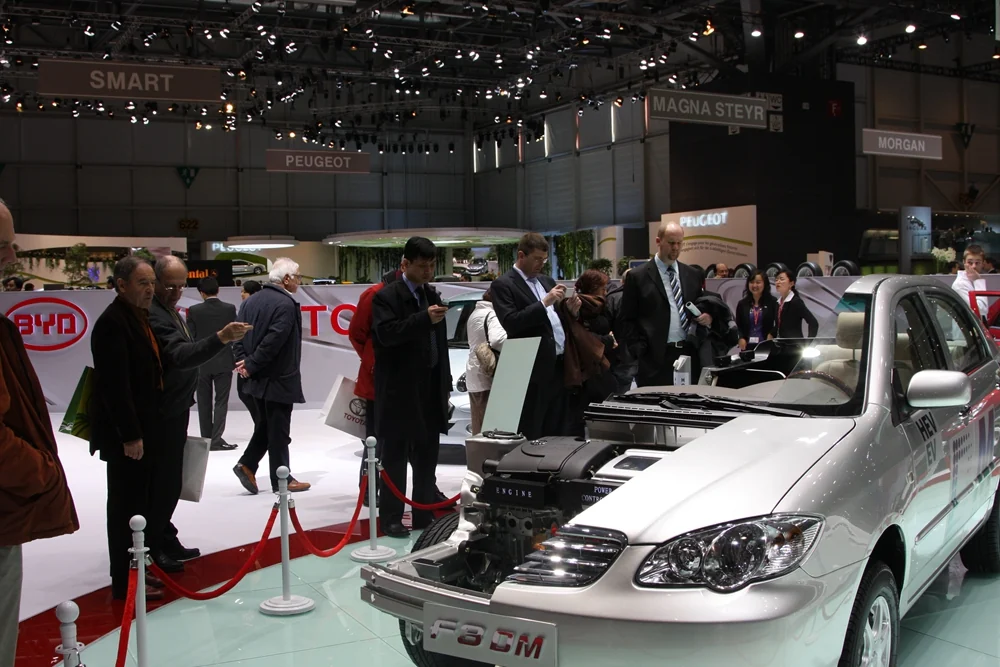
The F3DM, introduced in 2008, made the longer-term direction explicit. BYD describes it as the world’s first mass-produced plug-in-hybrid compact sedan and the first generation of its Dual Mode system. The historical importance lies less in its initial volume than in the architecture it represented. A plug-in hybrid allowed short electric driving while retaining a combustion engine for longer journeys, an approach later central to China’s rapid NEV adoption. It also demanded coordination among cells, battery management, power electronics, motors, engine control and vehicle software—the same integration problem BYD had been preparing to own.
Early arrival did not equal immediate market leadership. Charging infrastructure was immature, consumer understanding was limited and the early product carried the cost and complexity of two power systems. The F3DM should therefore be read as a technical and strategic milestone, not proof that BYD had already solved the economics of mass adoption.
The F3 also sits at the center of BYD’s most persistent historical controversy. The sedan was closely modelled on the ninth-generation Toyota Corolla — a resemblance widely noted at launch and documented in industry histories since. Contemporary accounts describe a systematic method behind it: the purchase and teardown of dozens of competitor vehicles for benchmarking, and an instruction to absorb what was not patented while designing deliberately around protected elements. The commercial logic was equally deliberate. The Corolla was one of the world’s best-selling cars, which meant a deep, accessible supplier base for components — allowing BYD to bring a familiar-looking sedan to market quickly and price it at roughly half of the foreign-brand models it resembled.
The commercial result anchored the company. Monthly F3 sales passed the 10,000 mark in early 2007; cumulative sales passed 100,000 within two years of launch, the fastest pace for a domestic sedan to that point according to industry accounts; and by 2009 BYD had become China’s best-selling domestic automaker. The episode is best read as documented industry history rather than either scandal or marketing claim: copying defined the starting point, and the money it earned was redirected toward original engineering — the same sequence Japan’s and Korea’s automakers had followed decades earlier.
2008–2009: what the Berkshire-backed investment actually proves
Stories about BYD’s relationship with Warren Buffett and Charlie Munger often overtake the transaction itself. The documentary record is clear. On September 27, 2008, BYD announced that MidAmerican Energy Holdings, then part of Berkshire Hathaway, would subscribe for 225 million new H shares at HKD8 each. Completion occurred on July 30, 2009. The subscription represented about 9.89% of BYD’s enlarged share capital.
The investment mattered in three ways. It brought long-term capital during a global financial crisis, increased international attention and provided external validation of BYD’s battery-and-vehicle thesis. What it did not do was remove execution risk. BYD still had to improve its cars, build a stronger brand, finance research and survive weak profit years. Later accounts of individual conversations may illuminate personalities, but they should not be used as substitutes for the signed terms, completion date and ownership disclosed to the exchange.
2007–2011: the copycat product wave — and the channel crisis
The success of the F3 was followed by the fastest product expansion in BYD’s history — a second wave of models widely described as drawing on familiar foreign templates: the F0 mini-car on the Toyota Aygo; the F6 sedan on the Honda Accord (running a Mitsubishi engine); the S6 SUV on the Lexus RX; and the M6 MPV on the Toyota Previa. Derivatives such as the F3R, G3 and L3 filled the gaps around them. Between 2007 and 2011 this portfolio — built more on reverse engineering and cost control than on original design — carried most of BYD’s volume. The S6 in particular became one of the group’s best-selling models of the period and was marketed on its strong domestic crash-test performance.
Ambition soon outgrew the distribution system meant to carry it. BYD split its retail channel into four networks (A1–A4), each selling a separate slice of the line-up, and expanded to more than a thousand primary dealers — reportedly approaching the scale of the Volkswagen joint-venture networks of the time. A 2010 sales target of 800,000 units, following 448,000 sales in 2009, was pushed down through assigned quotas and rebate structures that rewarded dealers for taking vehicles rather than for retailing them.
The result was the first serious internal crisis of the automaker era. In April 2010 a leading dealership exited the network; by late 2010 several hundred had followed, with one contemporaneous count putting the figure at 308 outlets — about 22.6% of the system. Inventory pressure, cross-network competition and weak margins on slower models were the proximate causes; the company initially attributed part of the problem to competitor interference before acknowledging planning errors of its own. At a dealer conference in September 2010 the sales chief publicly apologised, targets were cut and wholesale volumes reduced. At the 2011 shareholders’ meeting Wang Chuanfu described the 2009 sales strategy as a mistake — dealer quantity prioritised over dealer quality — and announced a three-year adjustment covering the channel, brand investment and product quality; the network was later cut from more than 1,200 outlets to roughly 800.
Seen at distance, the episode matters twice over. It shows that BYD’s hard years were not only technological: a fast-growing product line can stumble as easily through distribution and governance as through engineering. And it explains the shape of what followed — retrenchment at home, channel and capital discipline, while the electric-vehicle programmes stayed funded for the decade that would eventually commercialise them.
2010–2012: the taxi-first EV experiment — e6, K9 and the Shenzhen crash
While the F3 family funded the business, BYD put electrification on real roads through a deliberate channel: fleets first. The approach was to prove reliability under daily commercial use — taxis and buses — before selling battery cars to ordinary families. The e6, a five-seat electric crossover using an iron-phosphate (LFP) battery, entered taxi service in Shenzhen on 17 May 2010; with pilot vehicles that had gone into operation earlier that month, Shenzhen became the first city in the world to run electric taxis at any scale. BYD quoted a range of about 300 km — the longest of any series-produced electric car at the time — consumption near 21.5 kWh per 100 km, and charging from a household socket. The K9 electric bus followed into trial operation in Shenzhen and Changsha in early 2011 on city bus routes.
The fleet programme produced exactly the operating data BYD needed. By 2011 the company reported that the Shenzhen e6 taxi fleet had accumulated more than 3 million kilometres, with individual cars past 100,000 km. The same vehicles later became a widely cited reference for battery durability after retirement. The first chapter of the experiment, however, ended with its hardest public test.
On 26 May 2012 a Nissan GT-R travelling at extreme speed struck an e6 taxi from behind on a Shenzhen expressway — by the later official reconstruction, still above 180 km/h at the moment of impact. The taxi was destroyed, its driver and two passengers died, and the vehicle burned. Barely two years after the model’s launch, the crash pulled the safety of electric vehicles into a national debate, and BYD’s shares fell sharply on the first trading day afterwards.
In August 2012 a panel of 13 independent experts, organised under Shenzhen’s quality-inspection authority and led by the China Automotive Technology and Research Center, published its findings. The battery did not explode, and 72 of the vehicle’s 96 individual cells — about three-quarters — never ignited. The fire had a different origin: the extreme two-stage impact deformed the rear structure and battery tray, short-circuiting high-voltage wiring against the body, and the resulting electric arc ignited interior materials. The panel found no defect in the vehicle’s safety design and noted that the mechanical forces involved would have been fatal in any vehicle. The case — with the behaviour of the battery chemistry documented in unusual detail — became one of the most-cited references in China’s electric-vehicle safety discussions, and the e6 taxi fleet continued to operate.
2011–2019: the difficult years that the success story often removes
BYD’s current scale can make the 2010s look like a straight line from F3DM to Blade Battery. The audited record shows a much rougher transition. Revenue in 2012 was below 2011, while profit attributable to owners of the parent fell from RMB1.385 billion to only RMB81 million. Profit recovered later, but 2019 again delivered just RMB1.614 billion on RMB121.778 billion of revenue. These were not small startup losses; they were pressure points inside a large industrial group.
The period exposed the cost of trying to compete in conventional vehicles while funding electrification, batteries, power electronics and new-energy systems. It also challenged BYD’s brand. Technical ambition did not automatically produce consistent product execution or premium pricing. The responsible historical conclusion is not that every decision was vindicated from the start. It is that BYD retained enough cash-generating operations, capital access and engineering commitment to continue through a long interval in which the payoff remained uncertain.
| Year | Revenue | Profit attributable to parent | R&D expense | What the year shows |
|---|---|---|---|---|
| 2011 | 46.312 | 1.385 | 1.374 | BYD was already large, but profitability was modest. |
| 2012 | 44.381 | 0.081 | 1.150 | Revenue contracted and parent profit nearly disappeared. |
| 2015 | 77.612 | 2.823 | 1.998 | NEV growth improved results, but the group was still far from today’s scale. |
| 2019 | 121.778 | 1.614 | 5.629 | R&D expense was several times parent profit before the 2020s product cycle. |
2020–2021: Blade Battery and DM-i made old research commercially legible
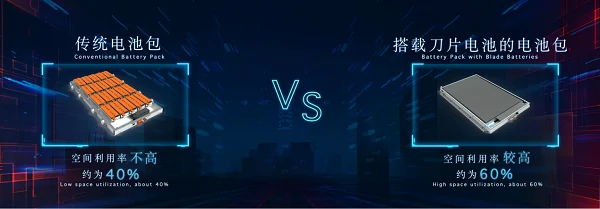
BYD launched the Blade Battery in March 2020 as a new form of lithium iron phosphate pack. The company said the cell’s long, blade-like format enabled a module-free pack structure and raised pack-volume utilization by more than 50%. It also publicized nail-penetration results as evidence of thermal safety. Those statements are manufacturer claims from a launch event, not an independent certification of every pack and vehicle. Their strategic meaning is still substantial: BYD turned a long commitment to LFP chemistry into a simple story about safety, packaging and durability that buyers could understand.
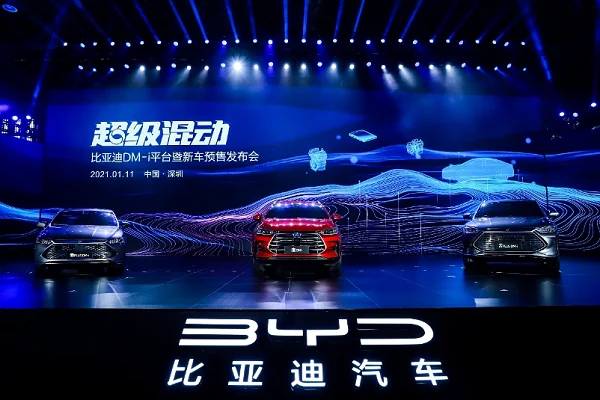
The DM-i Super Hybrid platform launched in January 2021. BYD presented launch models with fuel-consumption claims as low as 3.8 litres per 100 kilometres and combined range above 1,200 kilometres. Again, the figures describe the specified launch conditions, not a universal real-world result. More important was the system priority: electric drive carried more of the driving task, while the engine was optimized around efficient electricity generation and high-efficiency operating zones.
Blade Battery and DM-i succeeded together because they addressed different adoption barriers. Blade supported a safety-and-packaging narrative for battery vehicles; DM-i allowed buyers without perfect charging access to gain much of the electric-driving experience. The combination broadened BYD’s market rather than forcing every customer into one drivetrain.
2022: BYD stopped gasoline-only production—but did not abandon combustion engines
BYD announced on April 4, 2022 that it had stopped producing conventional gasoline-only vehicles, with the last one rolling off the line in March. The company would focus on battery-electric vehicles and plug-in hybrids and continue providing parts and after-sales support to existing gasoline-car owners.
The wording matters. BYD did not eliminate every combustion engine from its products: plug-in hybrids retain an engine. It exited the category in which propulsion depends only on gasoline. The decision concentrated product planning, factories, purchasing and marketing around electrified architectures while preserving the transitional flexibility of DM hybrids. It also gave BYD a clear identity at a time when many global automakers still treated EVs as a parallel line.
Vertical integration: BYD’s central advantage and its permanent burden
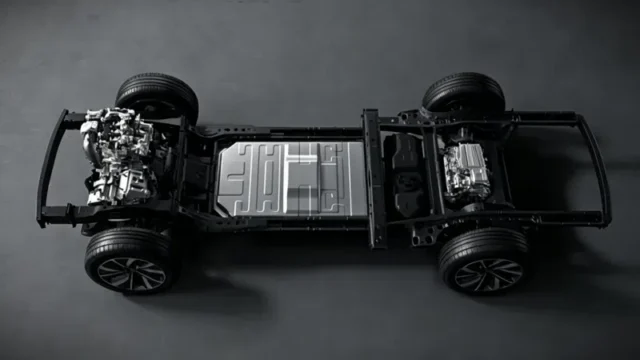
BYD’s operating model spans battery cells and packs, power semiconductors, electric motors, power electronics, vehicle control, platforms, a growing share of assisted-driving hardware and software, and extensive manufacturing equipment. The point is not that every component is made internally in every vehicle. The strategic point is that BYD owns enough critical technologies to coordinate performance, cost and production without waiting for a chain of independent suppliers.
Integration can shorten development loops. A battery team can work directly with pack, chassis and vehicle-control teams. Purchasing pressure is reduced when a constrained component is available within the group. Shared technologies can be spread across large volumes and multiple brands. During rapid product cycles, those feedback loops can matter as much as the nominal specification of one component.
But integration is not free. It requires capital, engineering headcount, factories and management systems across many technical domains. A specialist supplier can distribute research cost across customers; BYD must keep its own solution competitive while also operating the finished-vehicle business. When technologies or market preferences change, a deeply integrated company can carry more stranded investment. BYD’s scale makes the model plausible, but scale also magnifies quality, inventory and coordination failures.
The detailed architecture is maintained in BYD Technology Explained. Battery chemistry and commercialization status belong in the EV Battery Technology Owner; charging rollout claims are tracked in the BYD FLASH Charging Owner; and driver-assistance boundaries are maintained in BYD’s intelligent-driving evidence page.
The four-brand matrix: one industrial core, different buyers
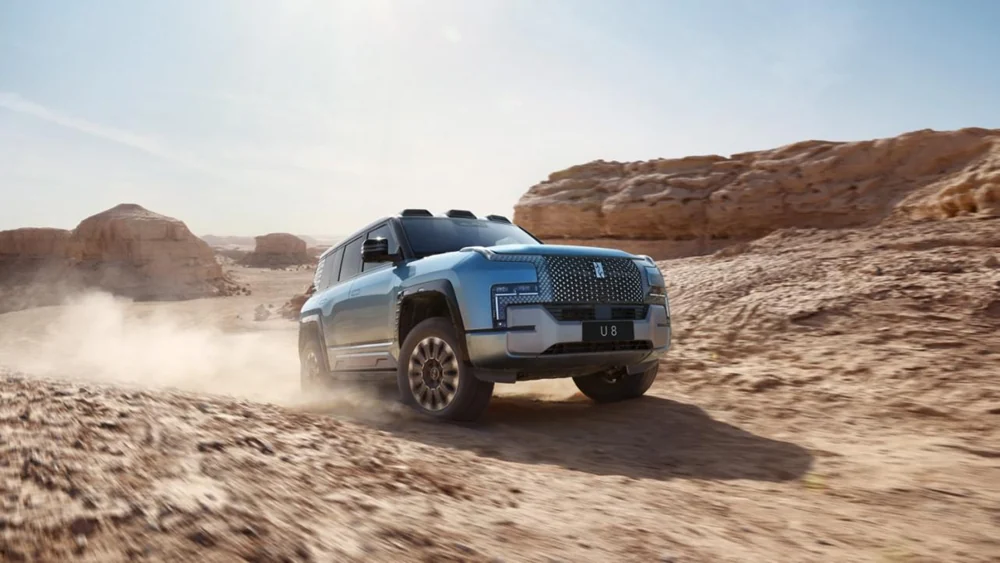
BYD’s 2025 annual report describes a vehicle portfolio built around BYD, Denza, Fangchengbao and Yangwang. The structure is more than a list of badges. It tests whether the group’s batteries, electrified drivetrains, electronics and manufacturing can support very different price points and customer identities without making the core BYD marque carry every positioning task.
| Brand | Primary role | What it tests | Historical boundary |
|---|---|---|---|
| BYD | Core high-volume marque spanning BEVs and plug-in hybrids. | Whether scale, cost control and frequent product cycles can defend the mass market. | “BYD” also names the listed group; context must distinguish group from marque. |
| Denza | Premium technology and comfort brand. | Whether BYD’s systems can support higher prices, design expectations and premium retail. | Denza’s ownership and positioning changed over time; current role should not be projected backward. |
| Fangchengbao | Personalized and off-road-oriented electrified vehicles. | How hybrid systems and body-control technology perform in lifestyle and rugged-use segments. | Product capability varies by model; brand identity is not proof of off-road performance. |
| Yangwang | Top-end technology showcase. | Whether unusual propulsion, body control and performance systems can create a credible luxury halo. | A flagship’s technical spectacle does not establish broad premium profitability. |
2021–2025: scale, research spending and the new financial tension
BYD’s 2025 audited revenue was RMB803.965 billion, not RMB777 billion. RMB777.102 billion was the 2024 figure. Profit attributable to owners of the parent fell 18.97% in 2025 to RMB32.619 billion even as revenue increased 3.46%. That combination captures the latest strategic tension: BYD achieved global industrial scale while price competition, overseas expansion and investment pressured returns.
Research figures also require definition. The 2025 annual report describes company R&D investment of RMB63.4 billion and cumulative investment above RMB240 billion, while the audited income statement records RMB57.978 billion of R&D expense. The difference can reflect accounting treatment, including capitalized development expenditure. This page uses the audited expense series for year-to-year comparison and labels the broader RMB63.4 billion number as company-reported investment.
| Year | Revenue | Profit attributable to parent | R&D expense | Interpretation |
|---|---|---|---|---|
| 2021 | 216.142 | 3.045 | 7.991 | The pre-scale base before the most rapid volume expansion. |
| 2022 | 424.061 | 16.622 | 18.654 | Revenue nearly doubled as electrified product demand accelerated. |
| 2023 | 602.315 | 30.041 | 39.575 | R&D expense moved above parent profit. |
| 2024 | 777.102 | 40.254 | 53.195 | Large-scale domestic and overseas expansion continued. |
| 2025 | 803.965 | 32.619 | 57.978 | Revenue rose, but profit and gross margin declined amid competition and expansion costs. |
Other 2025 indicators show why simple sales rankings are incomplete. Gross margin fell to 17.74% from 19.44% in 2024. Operating cash inflow fell to RMB59.136 billion from RMB133.454 billion. Borrowings rose to RMB113.435 billion from RMB28.584 billion, and inventory days increased to 72 from 61 as overseas expansion and shipping extended the operating chain. These figures do not imply financial distress by themselves, but they show that global scale consumes cash and balance-sheet capacity.
2026 update (incorporated October 11, 2026). The tension sharpened in the first half of 2026: revenue of RMB344.815 billion (−7.13% year on year) and net profit attributable to the parent of RMB12.325 billion (−20.54%), with second-quarter profit up 29.66% year on year as margins recovered. Overseas revenue reached RMB181.268 billion, or 52.6% of the total — the first time international business exceeded half of group revenue — while first-half exports rose 67.8% to 792,000 vehicles and capital expenditure fell 44.5% to RMB44.7 billion as the domestic capacity build-out concluded. Monthly sales then recovered through the year: September 2026 deliveries of 463,561 new-energy vehicles were up 16.99% year on year, with 180,700 exported, taking the nine-month total to 3,131,576 — still 3.94% below the same period of 2025, illustrating how much of the group’s growth now depends on markets outside China.
From Chinese exporter to multinational manufacturer
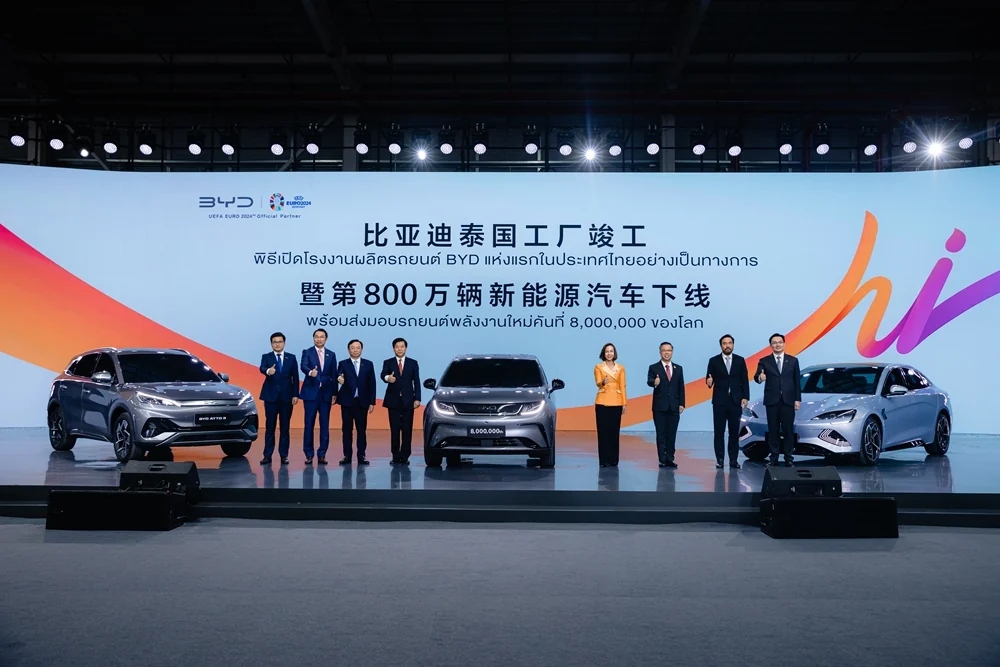
BYD’s internationalization has moved beyond shipping vehicles from China. The Thailand passenger-vehicle plant opened on July 4, 2024 after a 16-month build. BYD states that it has annual capacity of 150,000 vehicles and includes stamping, welding, painting, assembly and component production; the company projected 10,000 jobs. In Brazil, the first locally produced passenger vehicle rolled off the line in July 2025. The 2025 annual report said preparation for the Hungary passenger-car plant was progressing.
The company describes an overseas ecosystem combining R&D, manufacturing, logistics and sales. The logic is clear: local factories can reduce delivery time, answer local-content rules and tariffs, adapt products and strengthen political legitimacy. The execution burden is equally clear. Plants must ramp quality, develop suppliers, train workers and operate under different labour, environmental and trade regimes.
In 2025, overseas revenue reached RMB310.638 billion, or 38.65% of group revenue, up from RMB221.802 billion and 28.55% in 2024. BYD sold 4.60 million NEVs and reported 1.05 million overseas exports. “Exports,” “overseas sales,” local registrations and locally built output are not interchangeable metrics; each describes a different stage of the commercial chain.
Governance: founder control inside a public industrial group
Wang Chuanfu remains BYD’s chairman, executive director and largest shareholder. The 2025 annual report listed his ownership at 17.06%. That position provides continuity across long research cycles and major capital decisions. It also creates key-person and capital-allocation risk: a culture built around one founder’s technical conviction must still challenge assumptions, develop successors and govern increasingly complex international operations.
BYD is not legally a founder’s private workshop. It has executive, non-executive and independent directors, board committees, exchange disclosure and audited financial statements. Long-time shareholders and directors including Lv Xiangyang and Xia Zuoquan are part of the governance history. The important analytical question is how formal oversight and institutional engineering culture balance Wang’s concentrated strategic influence.
BYD reported more than 120,000 engineers in 2025, more than 71,000 patent applications and more than 42,000 granted patents. Those figures indicate that the company’s technical capacity is institutional rather than personal. They do not eliminate founder dependence. Engineering organizations still require priorities, budgets and mechanisms for abandoning weak projects.
Failures, trade-offs and risks: what a complete history must retain
Early technical leadership did not guarantee early commercial success. The F3DM anticipated a category but arrived before charging, consumer demand and cost structures were ready. Its importance is historical; its initial market performance should not be romanticized.
The 2010s contained severe profitability pressure. The 2012 and 2019 filings show that scale and technical spending could coexist with very weak parent profit. BYD survived the transition, but the outcome was not inevitable.
Integration creates concentration risk. Control of batteries, electronics, platforms and manufacturing reduces supplier dependence but makes BYD responsible for more failure modes. A defect or mistaken technical bet can propagate across multiple models and brands.
Price competition can turn scale into margin pressure. The 2025 decline in gross margin and parent profit, combined with higher borrowings and inventory days, demonstrates that unit growth does not automatically improve financial quality.
Overseas factories are political and operational projects. Local production may reduce tariff exposure, but factory ramp, labour standards, supply-chain localization and shifting trade policy can delay returns. Announced capacity is not the same as sustained output.
Premium brands have a different economics. Yangwang, Denza and Fangchengbao can create halo effects and reuse technology, yet premium retail, residual value and service expectations cannot be solved by hardware alone.
Driver assistance must remain within legal boundaries. Large data volumes and powerful computing do not make a consumer car legally autonomous. Claims should be tied to the specific feature, market, driver-responsibility rule and approval status.
Why BYD’s history matters beyond BYD
BYD is one of the clearest ways to read China’s new-energy-vehicle history because its transformation connects several national shifts in one company: materials research, export manufacturing, public-market capital, automotive licensing, battery industrial policy, city-level investment competition, supply-chain localization and a vast consumer market. BYD did not create those conditions alone, and it was not the only company to use them. CATL, Geely, SAIC, Changan, Huawei-linked ecosystems, NIO, XPeng, Li Auto and many suppliers followed different routes. BYD’s distinguishing feature was the breadth of the stack it attempted to control.
That makes the company neither a simple national champion nor a founder fairy tale. It is an industrial organization shaped by Wang’s engineering instincts, thousands of managers and engineers, policy incentives, customers, public shareholders and repeated competitive pressure. Its record includes technological persistence, capital-market discipline, near-zero-profit years, rapid scale and new governance burdens.
The next phase will test whether the system that succeeded in China can remain coherent across many brands and countries. The relevant measures are not only annual deliveries. They include overseas registrations and local output, margins and cash conversion, quality, research productivity, charging utilization, regulatory approval, supplier health and the ability to build leadership beyond the founder.
Read the China investment analysisWhy provinces compete for BYD projects and what they are actually asking for.
Enter the BYDToday Knowledge CenterBrand, founder, policy and technology Owners across China’s NEV industry.
See how BYDToday verifies claimsSource hierarchy, evidence boundaries, dates and corrections.
Frequently Asked Questions
When was BYD founded: 1994 or 1995?
BYD’s current corporate timeline dates its founding and registration to November 18, 1994. Wang Chuanfu’s official biography and many company histories describe February 1995 as the founding or operating start. This page preserves both official formulations rather than treating one as an error.
What did Wang Chuanfu study?
BYD’s official biography says Wang earned a bachelor’s degree in metallurgical physical chemistry in 1987 and a master’s degree in engineering from the Beijing Nonferrous Metals Research Institute in 1990. He then worked in the nonferrous-metals research system and managed Shenzhen Beagle Battery.
Why did a battery company buy an automaker?
BYD acquired 77% of Xi’an Qinchuan Automobile in 2003 for RMB269.5 million. The acquisition provided a vehicle manufacturing base through which BYD could integrate batteries, motors and power electronics. The strategic interpretation is strong, but the transaction itself did not guarantee automotive success.
What was important about the BYD F3DM?
The 2008 F3DM was an early mass-produced plug-in-hybrid compact sedan and the first generation of BYD’s Dual Mode system. It demonstrated the company’s intended architecture before plug-in hybrids became mainstream, although early arrival did not mean immediate mass-market success.
Did BYD stop making combustion-engine cars in 2022?
BYD stopped producing gasoline-only vehicles in March 2022 and focused on battery EVs and plug-in hybrids. Plug-in hybrids still contain combustion engines, so the decision was an exit from ICE-only vehicles, not from every engine.
Why is BYD vertically integrated?
Internal control of batteries, motors, power electronics, semiconductors, platforms and software can reduce cost, shorten development loops and limit supplier dependence. The trade-offs are high capital needs, greater organizational complexity and exposure when an internal technical bet is wrong.
Which major vehicle brands belong to BYD?
BYD’s current vehicle-brand portfolio comprises the core BYD marque, Denza, Fangchengbao and Yangwang. They target different price and use segments while sharing parts of the group’s battery, drivetrain, electronics and manufacturing system.
How large was BYD in 2025?
BYD reported RMB803.965 billion of revenue, RMB32.619 billion of profit attributable to the parent, 4.60 million NEV sales and 1.05 million overseas exports for 2025. Parent profit fell even as revenue rose, illustrating the cost and competitive pressure of global expansion. By September 2026 the group had sold 3,131,576 NEVs year to date, still 3.94% below the same period of 2025, with overseas revenue above half of the total for the first time in the first half.
Was the F3 a copy of the Toyota Corolla?
The F3 was closely modelled on the ninth-generation Toyota Corolla, a resemblance widely noted from launch and documented in industry histories. Contemporary accounts describe extensive benchmarking of competitor vehicles and deliberate engineering around patented design elements, which helps explain why no intellectual-property action followed. BYDToday treats the design relationship as documented industry history: it defined BYD’s commercial starting point, and the volume it generated helped fund the research that later became the company’s differentiator.
What happened in the 2012 Shenzhen e6 crash?
On 26 May 2012 a speeding Nissan GT-R struck a BYD e6 electric taxi from behind at very high speed; three people in the taxi died and the vehicle burned. A 13-expert panel led by the China Automotive Technology and Research Center concluded in August 2012 that the battery did not explode (72 of 96 cells never ignited), that the fire began when impact damage short-circuited high-voltage lines and an electric arc ignited interior materials, and that the vehicle’s safety design showed no defect. The case became a reference point in China’s electric-vehicle safety debate.
Primary sources and evidence
- BYD Media, Wang Chuanfu official biography.
- BYD, current corporate timeline.
- BYD, Hong Kong listing information.
- HKEX, BYD 2003 interim report and Qinchuan acquisition accounting.
- BYD, older official company-history record.
- BYD, official innovation history, including F3DM.
- BYD, MidAmerican investment announcement in the corporate timeline.
- HKEX, completion of MidAmerican’s 225 million-share subscription.
- BYD, 2015 annual report and five-year financial record.
- BYD, 2019 annual report.
- BYD, 2020 Blade Battery launch.
- BYD, 2021 DM-i Super Hybrid launch.
- BYD North America, 2022 gasoline-only vehicle discontinuation.
- HKEX, BYD 2025 annual report.
- BYD, Yangwang brand launch.
- BYD, Thailand passenger-vehicle factory inauguration.
- BYD, 30th anniversary and 10 millionth NEV.
- BYD Company Limited, discloseable-transaction circular for the Xi’an Qinchuan acquisition (January 22, 2003) and 2003 interim results.
- Economic Daily (经济日报), Shenzhen begins operating zero-emission electric taxis, May 18, 2010.
- China Association of Automobile Manufacturers (CAAM), e6, F3DM and K9 demonstration-fleet operating statistics, 2011.
- Xinhua / CCTV, expert-panel findings on the Shenzhen “5·26” crash, August 2012; China News Service, investigation summary, August 6, 2012.
- China News Service, independent-brand history series: BYD (model and dealer-network history), November 2013.
- Tencent News, BYD’s 13 decisive moments (2010–2011 channel-crisis account).
- BYD Company Limited, September 2026 production and sales filing, HKEX, October 2026.
- BYDToday, Source Methodology and Editorial Policy.
Claim ledger: how to read the evidence
| Claim | Status | Evidence | Editorial treatment |
|---|---|---|---|
| Wang’s education and early research roles | Confirmed | Official biography | Reported directly. |
| BYD founded in 1994 or 1995 | Boundary | Two current official formulations | Both dates retained and explained. |
| Process redesign was an early advantage | Inference | Official history plus Chinese archival dossiers | Strategic pattern retained; dramatic cost anecdotes excluded. |
| 2002 listing terms | Confirmed | BYD investor information | Exact date, shares and price reported. |
| 2003 Qinchuan acquisition terms | Confirmed | HKEX interim filing | Exact interest, price and asset value reported. |
| F3DM was an early mass-produced PHEV sedan | Confirmed | BYD product history | Historical milestone separated from sales success. |
| MidAmerican invested for 225 million H shares | Confirmed | Announcement and completion filing | Transaction facts separated from later anecdotes. |
| Blade pack-volume improvement and nail test | Company claim | 2020 launch event | Always attributed to BYD. |
| DM-i 3.8 L/100 km and 1,200 km range | Company claim | 2021 launch specification | Launch condition, not universal real-world result. |
| BYD exited gasoline-only vehicles in 2022 | Confirmed | BYD announcement | PHEV combustion-engine boundary stated. |
| 2025 revenue, profit, R&D and sales | Confirmed | Audited annual report | Expense and broader investment definitions separated. |
| Thailand plant capacity and job projection | Company claim | Factory inauguration release | Capacity and jobs are not treated as utilization. |
| Vertical integration is BYD’s advantage | Inference | Product, financial and organizational record | Benefits and burdens presented together. |
| Founder continuity creates key-person risk | Inference | Ownership and governance record | Analytical risk, not a reported control failure. |
| F3 closely modelled on the Toyota Corolla | Confirmed | Contemporaneous industry coverage and subsequent histories; no company originality claim | Described as documented industry history alongside the pricing and capability gains it produced. |
| 2010–2011 dealer-network crisis | Boundary | Contemporaneous reporting and company statements at the 2011 shareholders’ meeting | Dealer-exit counts vary by source; reported ranges retained rather than a single figure. |
| 2012 Shenzhen e6 crash findings | Confirmed | Joint expert-panel conclusions published August 2012 | Cause attributed to crash severity and arcing; battery explosion excluded. |
| 2026 interim and September 2026 figures | Confirmed | 2026 interim report; HKEX monthly filing | Reported directly; monthly production and sales figures are unaudited as noted by the company. |